OSNO-VA: AI accountant
- Built an AI platform

AI for accountants: what actually works in 2026, from documents to tax compliance. Learn if AI replaces accountants and how to choose the right tool.
AI for accountants extracts details from source documents, prepares cards for 1C, helps reconcile statements, and finds discrepancies.
Start with one document flow and measure the time from receipt to a verified entry.
The accountant approves accounting rules and handles exceptions.
Below are practical scenarios, prompts, and criteria for choosing an assistant.
In a November 2025 survey by SberAnalytics and Sber Business Soft, accounting and financial reporting accounted for 55% of automation areas. The survey covered various tools, including EDI and CRM. For your project, choose an operation from the table and test it on real documents.
| Challenge | What the system prepares | What to check before acceptance |
|---|---|---|
| Source documents from EDI, PDFs, and scans | A card with details and a link to the original | The counterparty, document, amounts, VAT, and contract |
| Statements and payments | Transaction matching suggestions | Ambiguous allocations and split payments |
| Technical errors | A list of discrepancies and possible duplicates | Errors found and missed in the labeled sample |
| Federal Tax Service requirements | A draft explanation with links to accounting data | Facts, supporting grounds, and the final text before sending |
| Management report | A summary and deviations according to the report rules | Data completeness, calculations, and explanations of variances |
From January 1, 2026, Federal Tax Service Order No. ED-7-26/28@ dated January 20, 2025, abolished the previous XML formats for the goods consignment note and work completion certificate. For electronic versions exchanged through an EDI operator, UPD 5.03 may be used, approved by Federal Tax Service Order No. ED-7-26/970@ dated December 19, 2023. This does not require all primary documents to be converted to UPD: The Federal Tax Service explains, that paper and non-formalized electronic documents remain in use.
For automation, first classify incoming documents by type. Fields can be extracted directly from XML; scans require recognition, while PDFs require text extraction or OCR depending on their contents. Then verify the details, amounts, and link to the accounting transaction. The presence of XML does not confirm that a document is correct or mean that the Federal Tax Service immediately detects every discrepancy.
In the corporate process, define who handles exceptions and authorizes entries in 1C. Retain the original document, verification result, and decision made. Measure the impact by the time required per accepted transaction, including recognition, verification, and corrections. Practical exchange steps are covered in the article about of Diadoc and 1C integration.
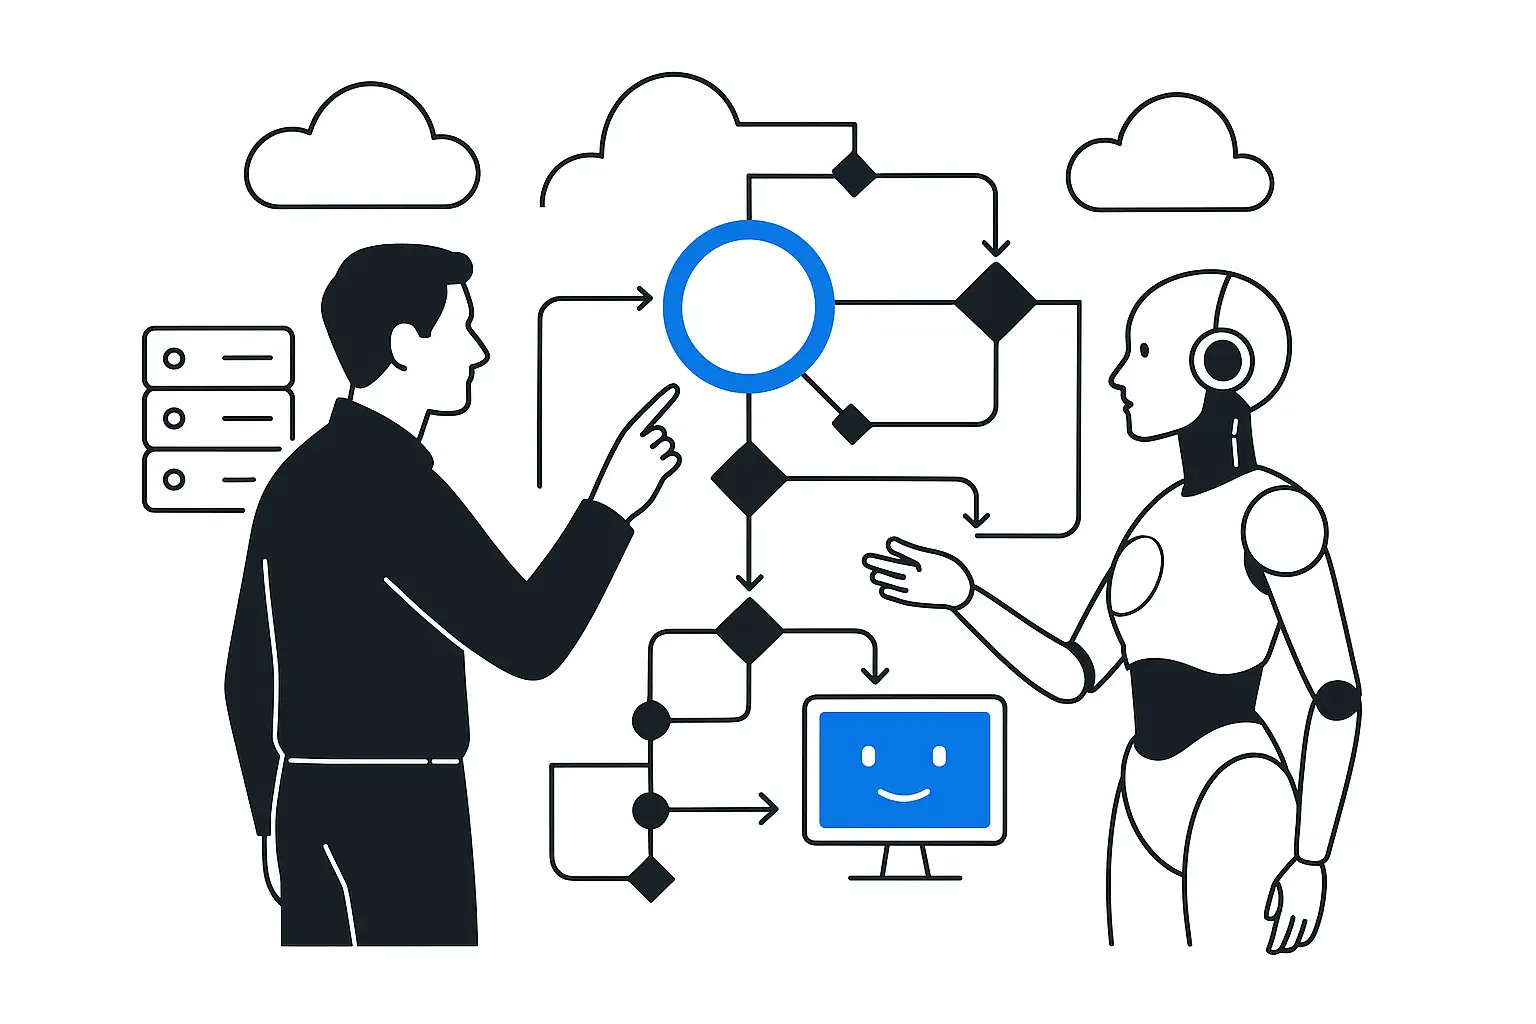
Checking source documents before entry into the accounting system
Input
Extract
Verification
Solution
The manager organizes accounting and document storage under Article 7 of Law No. 402-FZ. The accountant defines processing rules, reviews disputed transactions, and checks the result before the action required by the procedure. Automation should begin with repetitive operations where the checks can be described in advance.
Take comparable batches of documents by type, volume, and complexity. Separate XML, text-based PDFs, and scans. For each method, measure person-minutes per accepted document. Include preparation, verification, corrections, exception handling, and support time for the period.
For example, if processing 100 accepted documents took 500 person-minutes manually and 350 with an assistant, including support, the saving in this sample exercise was 1.5 minutes per document. Compare detail quality and the number of missed errors. Calculate model, infrastructure, and licensing costs separately.
The Financial University cites practitioners' estimates of automation potential and the share of technical errors. For a pilot, measure detection separately: how many known errors the system found, how many it missed, and how many false alerts the accountant reviewed.
| AI takes over | Left to a person |
|---|---|
| Recognition and posting of source documents | Accounting policy and methodology |
| Reconciliation of statements, registers, and settlements | Ambiguous interpretations of transactions and tax decisions |
| Technical error and duplicate detection | Signature and responsibility for reporting |
| Draft replies to FNS requests | Final text and what to send |
| Tracking document deadlines and completeness | Exceptions: nonstandard documents and counterparties |
| Drafts of recurring reports | Conclusions and decisions based on the numbers |
Take typical and disputed documents from one process. Measure manual processing and agree on acceptance criteria.
Compare the records with the originals. Verify the details, contract, and amounts, then handle re-uploading and recognition errors.
Assign an owner for exceptions. Check write permissions, the action log, and the processing spending limit.
Provide the settings, instructions, and test sample. During acceptance testing, the team changes a rule independently and restores processing after a failure.
The prompts below are written for use in a corporate environment or in a chat with anonymized data: do not paste employees' personal data or trade secrets into public AI services. Each prompt defines the role, inputs, and output format so the answer is verifiable rather than a free-form essay. Replace the square brackets with your own data.
A chat assistant helps review documents and prepare drafts.
The execution agent manages the queue, checks documents against configured rules, and performs permitted actions.
The process owner defines write and approval permissions.
The document queue, checks, and exception handling are shown on the page AI assistant for accountants.
| Criterion | Chat assistant | Execution agent |
|---|---|---|
| Working with 1C | no result or manual transfer | through a configured interface with assigned permissions |
| Audit trail | conversation history | log: source, rule, action, who approved |
| Policy-based review | depends on the prompt | rules are versioned and checked before release |
| Edge cases | remain in the conversation | Escalation to an accountant as an exception |
| Data layer | depends on the selected service | depends on model hosting, file storage, and integration |
| Suitable for | drafts and one-off checks | repeatable operations with checks |
Accounting implementation example - An AI accountant within the company environment. When choosing such a solution, test the full cycle on your own documents: intake, result verification, posting to 1C, and exception handling. Record costs and permissions at every stage.
Cases
FAQ
The assistant can perform extraction, reconciliation, and draft preparation. The accountant sets processing rules, checks exceptions, and confirms actions according to the procedure.
Take a sample of real documents and divide it by type. Measure the share of documents the system brings to an accepted result, how many corrections remain for a person, and how long the full cycle takes.
Request a data-flow diagram: where originals are stored, which fields the model can see, where logs go, and who has access to them. Start with drafts and check for duplicates and discrepancies. Grant write access to accounting records only after the required checks have been accepted.
For a chat, specify the input data, verification criteria, and response format. For a repeatable process, the accountant also describes accounting rules and exceptions.
Choose one repeatable task, such as extracting details from incoming invoices. Check drafts on a small sample and compare the total effort with manual work.
Automation data, practitioner assessments, and rules for working with source documents were verified on 10 November 2026.
SberAnalytics and Sber Business Soft, automation survey, January 22, 2026.
Financial University, practical use of AI in accounting, February 13, 2026.
CIS Federal Tax Service on consignment note and certificate formats from 2026.
Federal Law No. 402-FZ, Article 7 on organizing accounting.